
What Is a Car Finance Check?
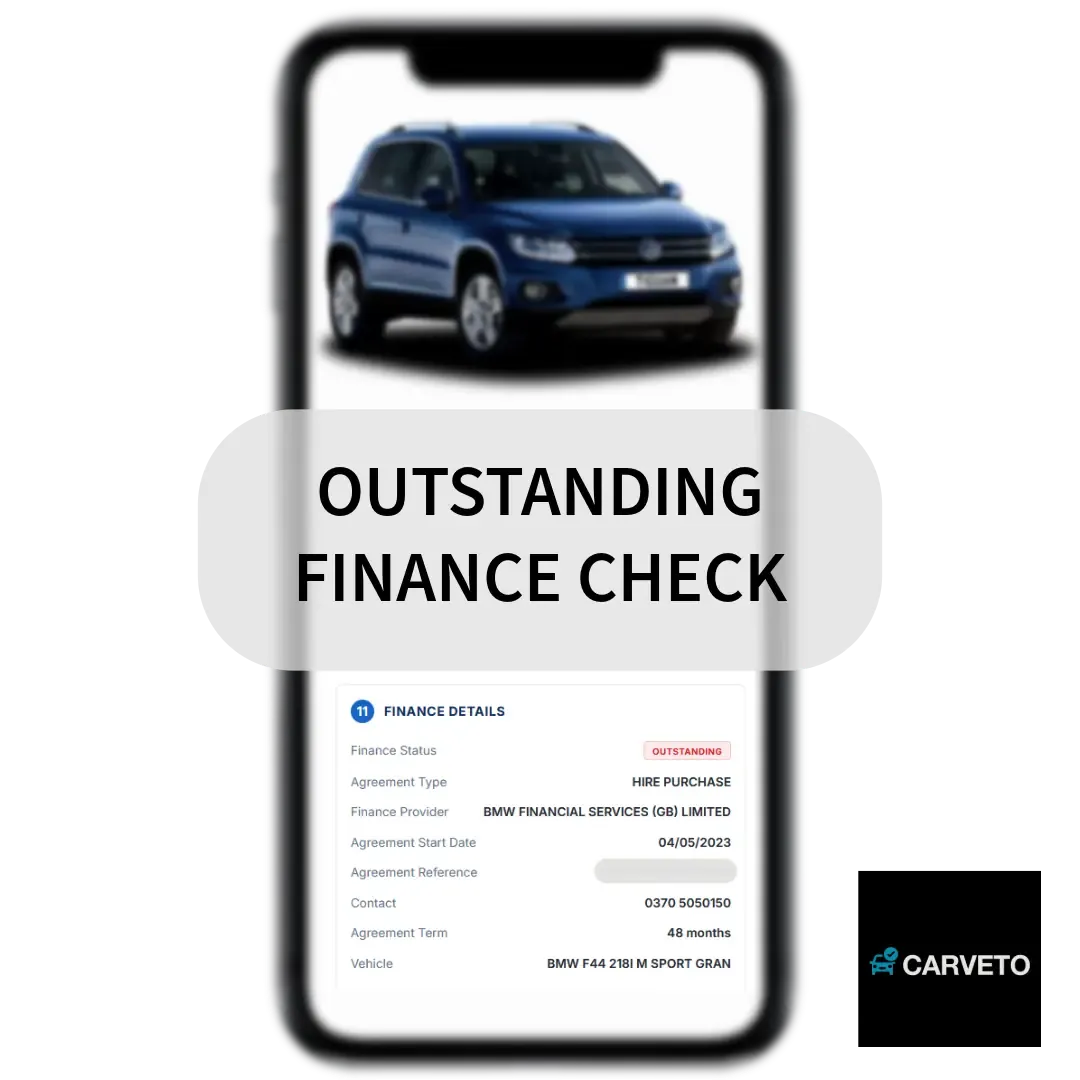
A car finance check is a vehicle history verification process that determines whether a used car has an active secured finance agreement recorded against its registration number or VIN (vehicle Identification Number).
A secured finance agreement gives the lender (the company providing the vehicle finance) legal rights over the vehicle.
The lender may retain rights over the vehicle until the balance is repaid and the agreement is formally settled.
Checking outstanding finance is important because an active finance agreement can affect the vehicle’s financial status and ownership.
CarVeto’s finance check can identify whether money is still owed to the lender before the purchase is completed.
Vehicle buyers can use this information to verify the vehicle’s financial status.
The results can help them identify potential financial issues before completing the purchase.
Car buyers can also raise concerns with the seller when outstanding finance is identified.
A car finance agreement finder can also form part of a broader vehicle history search.
A wider search may provide finance status, insurance write-off classification, theft records, and mileage history.
Reviewing these records alongside finance information gives buyers a broader view of the vehicle’s recorded history before purchase.
What Information Does a Car Finance Check Show?
A car finance check shows the vehicle’s outstanding finance status, agreement type, lender details, ownership status, and settlement requirements.
A vehicle finance check also provides structured details about any active or previously recorded secured finance agreement.
This information helps buyers identify outstanding finance and understand whether the vehicle can be purchased without unresolved finance issues.
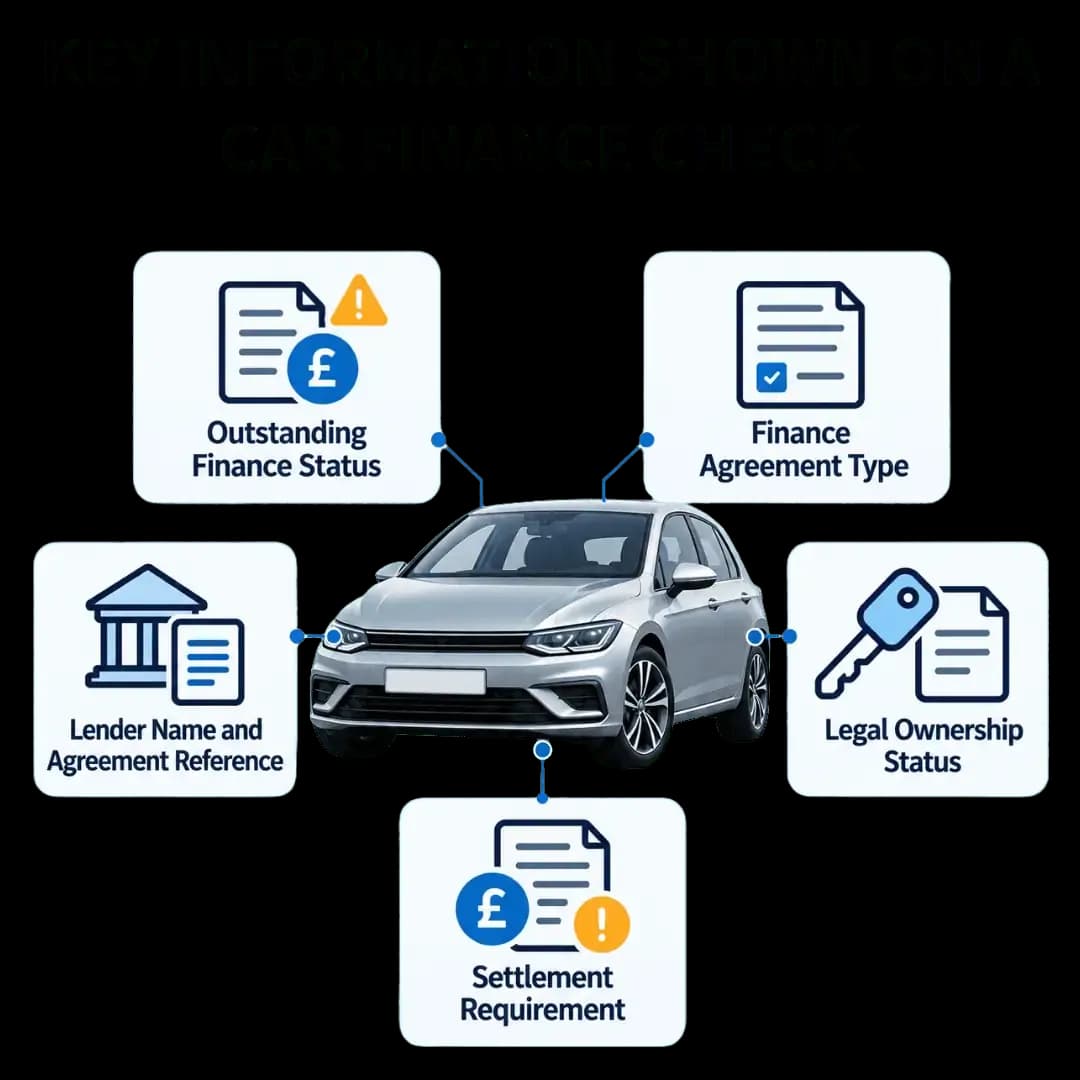
The key information included in a car finance check is given below.
- Outstanding Finance Status: The finance check confirms whether the vehicle’s finance agreement between the buyer and lender remains active or has been settled. The result does not provide the precise repayment figure. An active agreement may require further verification with the lender.
- Finance Agreement Type: The vehicle finance search identifies the type of finance agreement secured against the vehicle. Common types include Hire Purchase (HP), Personal Contract Purchase (PCP), and Lease Purchase (LP). Each agreement type affects when legal title transfers and when settlement is required.
- Lender Name and Agreement Reference: The finance check shows the company holding the secured interest in the vehicle and provides its agreement reference. Buyers can use these details to contact the lender and confirm the finance status or settlement requirements.
- Legal Ownership Status: The outstanding finance check clarifies whether the lender retains legal title to the vehicle under the relevant agreement. HP and PCP agreements generally retain lender title until the contractual balance is satisfied. Lease Purchase agreements retain lender title until the final payment, including any applicable balloon payment, has been made.
- Settlement Requirement: The finance check also specifies whether the outstanding finance must be cleared before legal title can transfer without restriction. Paying the seller alone does not remove the lender’s secured interest while the agreement remains active.
Real Customer Reviews of Our Car Finance Check
Customers have given CarVeto a 4.8-star rating on Trustpilot and Google Reviews, praising the accuracy and detail of its finance checks.
Vehicle buyers also value the clear finance information presented in our easy-to-read report.
Used car buyers also mention using outstanding finance and lender details to contact sellers and resolve finance issues before buying.
UK car buyers praise CarVeto’s customer support for providing prompt responses when they need clarification.
Very useful when buying a car
⭐⭐⭐⭐⭐
Angela Smedley
I am first time car, in my 50s and only just learning to drive. Was advised my driving instructor to get a car to have some practice in.
Saw a car I liked at Hilton Garage in Derbyshire and paid for it. I was a curious about it because there was no service history.
So glad I found your website because there was a warning on it about on going finance.
It me ages to sort it out and the garage had to call the finance company.
Hilton Garage in Derbyshire said they had never heard of you.
Will always use these. Incredible.
JP
⭐⭐⭐⭐⭐
Well what a relief we used this service on a van we were looking at purchasing.
Too good to be true usually is. Was in this case.
This report picked up its mileage had been wound back nearly 100k and there was still outstanding finance on it.
Apart from being absolutely gutted about it I’ve been saved from buying a van I thought was perfect and potentially avoided a whole heap of problems.
How to Check if a Car Is on Finance?
To check if a car is on finance, enter its registration number, run a vehicle history search, and review the finance status.
The search retrieves recorded finance information linked to the vehicle.
Follow the step-by-step process below to check if the car has a finance agreement.
- Enter the Vehicle Registration Number: Enter the car’s registration number into the vehicle registration field.
- Run a Full Vehicle History Search: Start a full vehicle history search to retrieve finance information linked to the vehicle’s registration record.
- Review the Finance Status Section: Review the finance status section to confirm recorded finance, identify the agreement type, and find the associated lender.
Our car finance check forms part of a broader car check.
This retrieves structured data connected to the vehicle’s registration record and recorded history.
What Types of Finance Appear on a Car Finance Check?
A car finance check shows different types of finance, including Hire Purchase, Lease Purchase, Conditional Sale, and logbook loans.
A car finance check records secured finance agreements registered against the vehicle as collateral.
These agreements create a security interest and remain visible in vehicle history data while active or previously recorded.
The finance types that appear on a finance agreement checker are listed below.
- Hire Purchase (HP): Hire Purchase is a secured agreement where the lender retains legal title until the contractual balance is fully paid. The vehicle buyer makes agreed payments throughout this contract, and ownership transfers after the final payment and formal settlement.
- Personal Contract Purchase (PCP): PCP is a secured agreement that includes a deferred final payment. The vehicle buyer makes regular payments, and the lender retains legal title until all contractual payments are satisfied.
- Lease Purchase (LP): Lease Purchase involves fixed instalments followed by a final balloon payment. Legal title remains with the lender until the balloon payment is made and this agreement is formally closed.
- Conditional Sale (CS): Conditional Sale is a secured agreement where ownership remains subject to the finance contract until required payments are completed. Legal title transfers after the buyer fulfils this agreement’s payment conditions.
- Unit Stocking / Dealer Stocking Loans: Unit stocking finance allows dealerships to fund vehicles held as inventory before retail sale. The lender retains security while the facility remains active, with security released after the dealership clears the finance. You can learn more about how this type of finance works by visiting our Car Stocking Loan page.
- Logbook Loans (Bill of Sale Agreements): A logbook loan uses the vehicle as collateral under a bill of sale arrangement. The borrower retains possession of the vehicle while the lender holds legal title until this loan is settled.
Finance That Does Not Appear on a Car Finance Check
The following finance types do not appear on a vehicle finance check.
- Unsecured Personal Loans: An unsecured personal loan is not secured against the vehicle, so it creates no recorded finance interest against the car. This loan remains separate from the vehicle’s financial history.
- Credit Cards and Overdrafts: Credit cards and overdrafts provide unsecured borrowing rather than vehicle-secured finance. Their balances therefore do not create a recorded finance interest against the car.
- Loans Secured Against Other Assets: A loan secured against another asset creates security over that specific asset instead. This loan therefore does not normally appear as finance recorded against the vehicle.
What Are the Risks of Buying a Car with Outstanding Finance?
The risks of buying a car with outstanding finance include vehicle repossession, ownership disputes, financial loss, and restrictions on reselling.
Buying a car with outstanding finance can expose the buyer to these legal and financial problems.
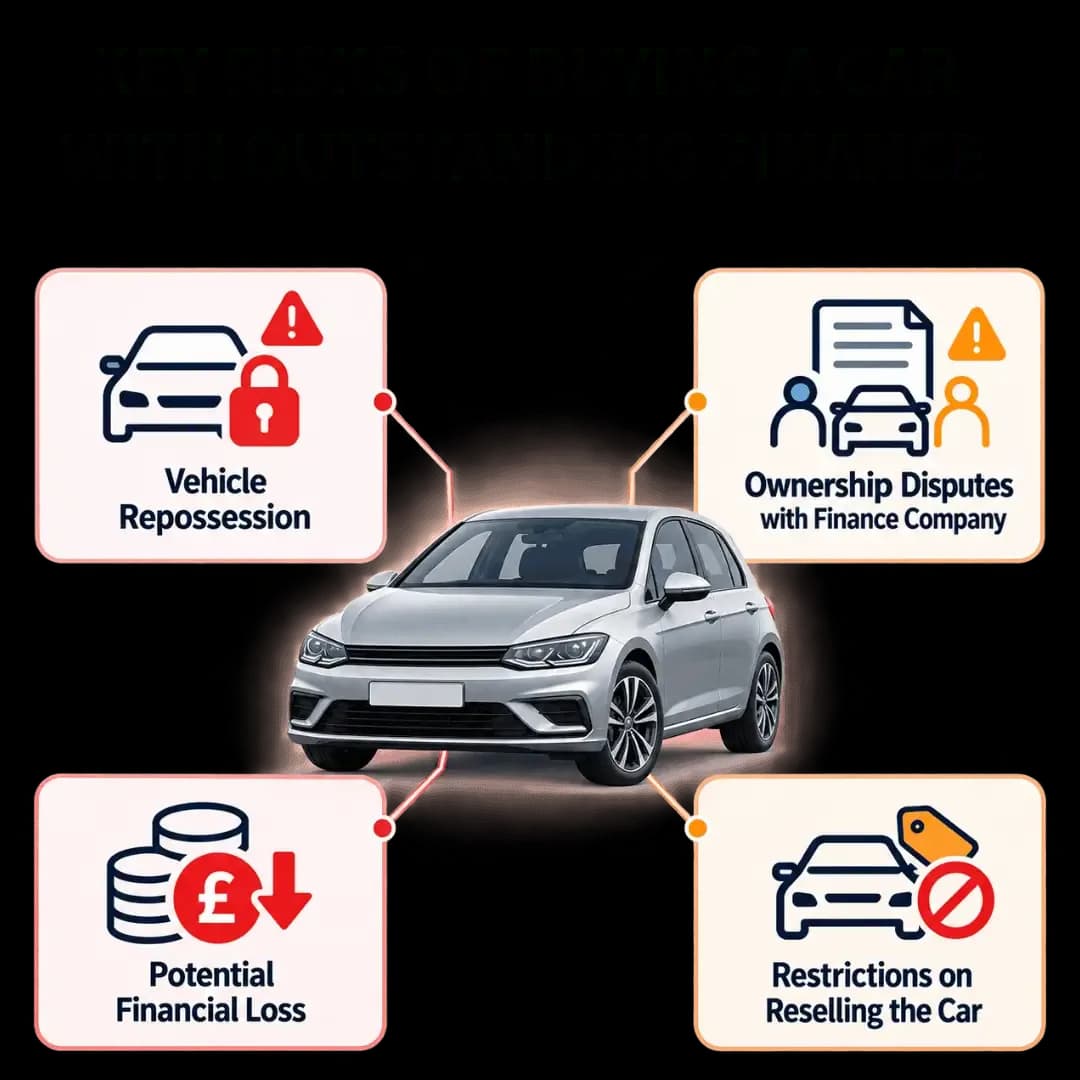
Purchasing a car with outstanding finance can have the following risks.
- Risk of Vehicle Repossession: The finance company may repossess the vehicle if its secured agreement remains active after the purchase.
- Ownership Disputes With the Finance Company: The car buyer may face a dispute because the finance company still holds enforceable rights over the vehicle.
- Potential Financial Loss: The vehicle buyer could lose money by paying the seller while the outstanding finance remains owed to the lender.
- Restrictions on Reselling the Car: The UK vehicle buyer may be unable to transfer the vehicle freely because the outstanding finance remains secured against it.
What Should You Do If a Car Finance Check Shows Outstanding Finance?
You should pause the purchase, contact the lender, settle the agreement, and confirm closure if a car finance check shows outstanding finance.
Completing the purchase before settlement can leave the vehicle subject to the lender’s repossession rights.
The following step-by-step process tells you what to do if a car finance check shows outstanding finance.
- Pause the Purchase: Do not complete the transaction while the vehicle remains subject to an active finance agreement.
- Contact the Lender: Contact the finance company to verify the agreement, outstanding balance, and current settlement requirements.
- Request a Settlement Figure: Ask the lender for a valid settlement figure and confirm the period for which it remains valid.
- Pay the Lender Directly: Arrange payment directly to the lender to settle the outstanding finance before completing the purchase.
- Get Written Settlement Confirmation: Obtain written confirmation from the lender confirming that the finance agreement has been fully settled and formally closed.
- Run a Fresh Finance Check: Run another finance check after settlement to confirm that the outstanding finance is no longer recorded.
What Does a Data Guarantee Actually Cover?
A data guarantee actually covers eligible financial losses caused by inaccurate finance information recorded in the reporting system.
CarVeto’s outstanding finance check includes a £10,000 Data Guarantee with the platinum report.
The guarantee applies only to information submitted and stored within the provider’s database when the finance check is performed.
The platinum report provides this guarantee against eligible inaccuracies in the recorded finance data.
The guarantee does not cover finance agreements that have not yet been reported or lender interests never registered in the reporting system.
It also excludes information updated after the check and private contractual disputes between vehicle buyers and sellers.
Coverage remains subject to the guarantee’s eligibility requirements and claim conditions.
It does not remove legal rights from unrecorded or later-updated finance agreements.
Frequently Asked Questions About Outstanding Car Finance Checks
No, you cannot check car finance for free because the car finance check is included with the Platinum Report.
Purchasing the Platinum Report gives you access to the vehicle’s recorded finance status and available agreement details.
The car finance check shows whether the car has any outstanding finance recorded against it.
A recorded finance agreement also includes available details about the lender and agreement type.
Vehicle buyers who need broader vehicle information can use our Car History Check to review additional records alongside the vehicle’s finance status.
Yes, a car finance check can miss active finance when the lender has not yet submitted or updated the agreement.
Finance checks depend on lender-reported data, so delays between agreement changes and database updates can affect the results.
Newly opened finance may not appear immediately because lenders can take time to report new agreements.
Recently settled finance may also remain recorded until the lender updates the relevant database.
Some lenders may not report to every vehicle data provider, which can create gaps between available records.
A missing finance record does not confirm that no secured finance exists.
It only confirms that no finance was found within the data sources searched at that time.
Yes, it can be illegal to sell a car with outstanding finance without clearing the debt or telling the car buyer.
Active finance can stop the seller from transferring the vehicle without the lender’s approval.
Selling the vehicle without settling the agreement can create contractual and legal risks for the seller.
Hiding the finance agreement may also amount to misrepresentation and expose the seller to civil consequences.
Vehicle buyers considering a car with outstanding finance should verify its legal ownership status before completing the purchase.
A car is considered clear of outstanding finance once the lender has received full payment and formally closed the finance agreement.
Full settlement can include the remaining balance, final balloon payment, and any applicable fees.
Payment alone does not confirm that the vehicle is clear of finance.
The lender must update its internal records and reporting feeds, confirming the agreement as settled or closed.
Finance checks may still show the previous finance status temporarily while lender and database updates are processed
The table below explains the differences between finance cleared and finance fully closed.
Finance Clearned | Finance Fully Closed |
|---|---|
The final settlement payment has been sent to the lender. | The lender has processed the payment and officially ended the finance agreement. |
The outstanding debt balance has been reduced to zero. | The lender has updated its internal records and reporting systems to show the agreement as closed. |
The finance account may still appear active while the payment is being processed. | The lender’s secured legal interest in the vehicle has been removed or discharged. |
Payment processing can take around 1-3 working days. | The customer can receive formal confirmation, such as a closure letter, from the lender. |
Vehicle finance records may still show the previous status temporarily. | Relevant vehicle history and credit records can be updated to reflect the settled status. |
Note: A vehicle is not legally free from finance risk until the agreement is fully closed and the lender’s secured interest has been discharged.