
Insurance Write-Off Categories: What Do Categories A, B, S, and N Mean?
UK insurance write-off categories (A, B, S, or N) describe the type and severity of damage a vehicle has suffered after an insurer declares it a total loss.
These categories show whether a vehicle must be destroyed, used for parts, or repaired and returned to the road.
A car or van is considered a write-off when an insurer determines that it is unsafe to drive or uneconomical to repair compared with its market value.
This decision follows an inspection of the vehicle, an assessment of its condition, and an estimate of the repair costs.
The insurer then assigns one of the 4 current write-off categories.
The current 4 car write-off categories are provided below.
- Category A: Scrap Only
- Category B: Break for Parts
- Category S: Structurally Damaged
- Category N: Non-Structurally Damaged
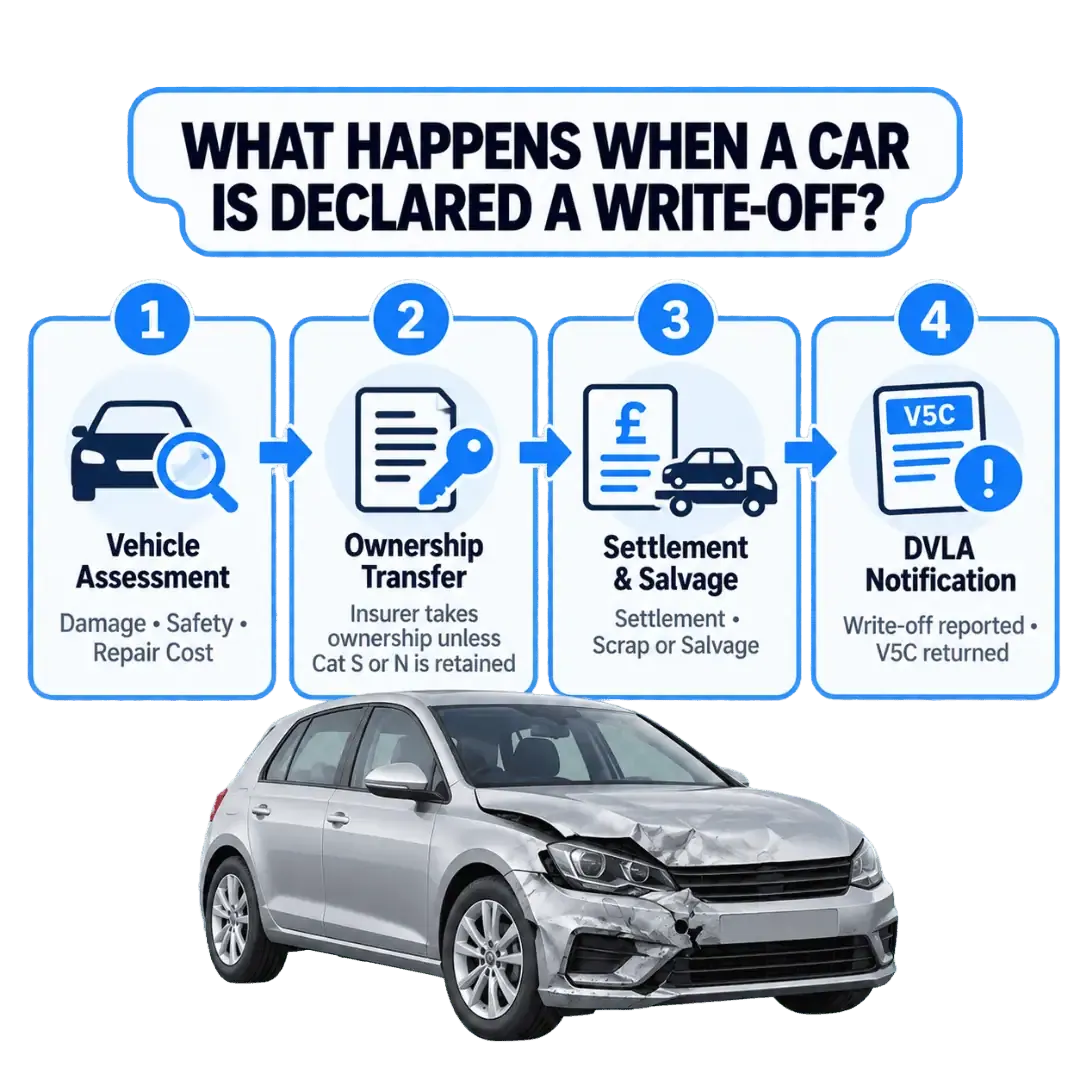
The current insurance write-off system replaced the former Cat C and Cat D categories with Cat S and Cat N in October 2017.
This new categorisation of defects focuses on the type of damage rather than primarily considering repair costs.
A vehicle’s category affects its legal status, road eligibility, DVLA (Driver and Vehicle Licensing Agency) records, insurance eligibility, market value and resale prospects.
It also influences the insurance payout, claims process, and whether an owner chooses to retain, repair, buy, or sell the vehicle.
Vehicle buyers considering a Category S or N car should assess these risks with the previous write-off and repair history.
What Is Meant by Insurance Write-Off?
An insurance write-off is a vehicle that an insurer considers a total loss because it is either too badly damaged to be safely returned to the road or beyond economical repair compared with its market value.
An insurance assessor inspects the vehicle and decides whether it should be written off based on the extent of the damage, safety, and repair costs.
A vehicle declared a write-off is recorded in MIAFTR (Motor Insurance Anti-Fraud and Theft Register) and assigned an insurance write-off category A, B, S, or N.
This status affects the insurance payout and claim process and may determine whether you can retain the vehicle through a buy-back.
It can also affect the vehicle’s MOT eligibility, DVLA records, market value, and future resale prospects.
The write-off category also determines whether the vehicle can be repaired, used for parts, or must be destroyed.
Category A vehicles must be destroyed, while Category B vehicles are only used for parts.
Category S and N cars can be safely repaired and returned to the road, although their write-off history remains on record.
What Are the Car Insurance Write-Off Categories in the UK?
The car insurance write-off categories in the UK are A, B, S, and N under the current ABI (Association of British Insurers) Salvage Code.
These insurance write-off categories indicate whether a vehicle must be scrapped, can provide salvageable parts, or can be repaired and returned to the road.
The write-off categories determine what happens to the vehicle after a total-loss decision, including its DVLA re-registration requirements, insurance eligibility, and resale potential.
The write-off category of a vehicle is recorded in MIAFTR and may also appear on a CarVeto vehicle history check.
The current car insurance write-off categories were introduced in 2017 by ABI, replacing the previous system of legacy categories C, D, and others.
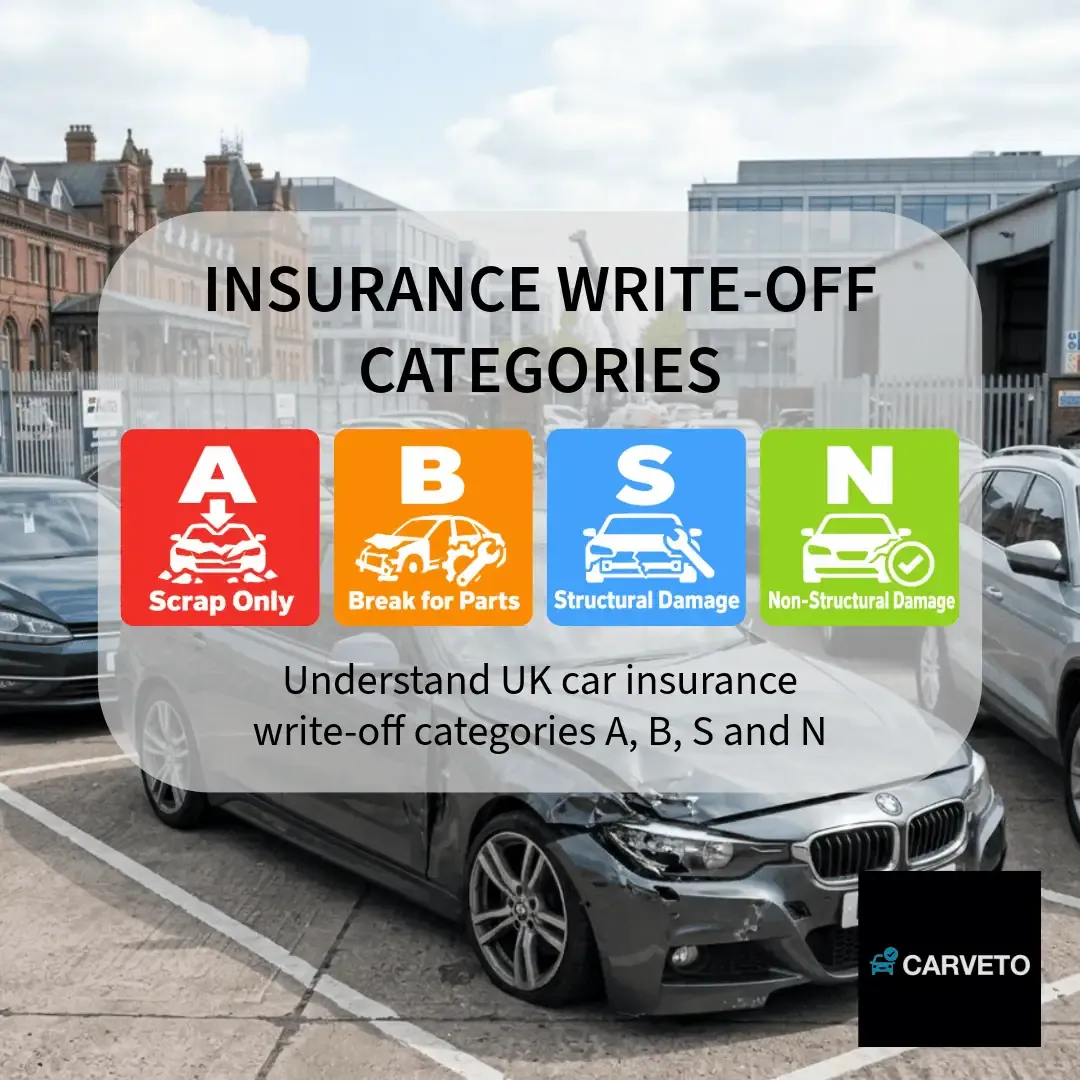
Category A: Scrap Only
A Category A car is the most severe insurance write-off category.
This classification applies when a vehicle is so badly damaged that it is considered irreparable and cannot safely return to the road.
It means that the entire vehicle must be crushed, with no parts permitted to be salvaged or reused.
The vehicle owner, therefore, cannot buy back the vehicle or reclaim any of its components.
Severe damage to the car from major fires, serious impacts, or extensive flooding results in a Category A classification.
Following the classification, the vehicle must be deregistered, and a COD (Certificate of Destruction) is issued as proof that the vehicle has been permanently destroyed and cannot return to the road.
Category B: Break for Parts
A Category B car is a vehicle that an insurer has declared a write-off because it cannot be safely repaired or returned to the road.
This vehicle’s body shell or chassis must be crushed, so the car itself cannot be rebuilt or put back on the road.
Licensed dismantlers recover usable components and sell them for use in other vehicles.
Category S: Structurally Damaged
A Category S car is classified as a repairable insurance write-off involving structural damage to areas such as the chassis, frame, crumple zones, or other components that affect crash safety.
This vehicle must be professionally repaired and restored to a roadworthy condition before it returns to the road.
A Category S vehicle is also insurable after maintenance and an MOT.
A cat S write-off retains a permanent write-off marker on the V5C logbook.
Buyers should therefore check the vehicle’s documentation and MOT history to verify its repair history, write-off status, and roadworthiness before purchasing.
Category N: Non-Structurally Damaged
A Category N car is a repairable insurance write-off involving non-structural damage.
This type of damage affects the electrics, interior, bodywork, or other components without compromising the vehicle’s structural integrity.
The extent of repairs varies, and some vehicles require more than cosmetic repairs.
A Category N vehicle can return to the road after the necessary repairs have been completed and it has been confirmed as roadworthy.
Re-registration of the vehicle is not required, although the write-off must still be recorded with the DVLA.
Non-structural damage does not necessarily mean minor or cosmetic damage, as safety-critical systems such as airbags and ABS (Anti-lock Braking System) can also be affected.
Buyers should therefore check the vehicle’s repair and MOT history carefully before purchasing it.
A Category N write-off lowers a vehicle’s resale value and reduces buyer confidence.
This vehicle is insurable, although insurance premiums may be higher because its previous write-off history can make it more difficult for insurers to assess and cover.
What Were the Old UK Insurance Write-Off Categories?
The old UK insurance write-off categories were Category C and Category D, which were used before October 2017.
This updated classification system replaced Category C with Category S and Category D with insurance write-off Category N. A
Category C car had structural damage that could be repaired, but the repair costs exceeded the vehicle’s value.
This vehicle required re-registration before it returned to the road.
A Category D car had non-structural damage that made the vehicle uneconomical for the insurer to repair, even though the repair costs were below its value.
Re-registration of this vehicle was not required, and the vehicle could legally return to the road after repairs.
What Happens When a Car Is Declared a Write-Off?
When a car is declared a write-off, the insurer assesses the vehicle, settles the claim, transfers ownership where applicable, and ensures the write-off is reported to the DVLA.
This process determines what happens to the vehicle and what you need to do as the owner.
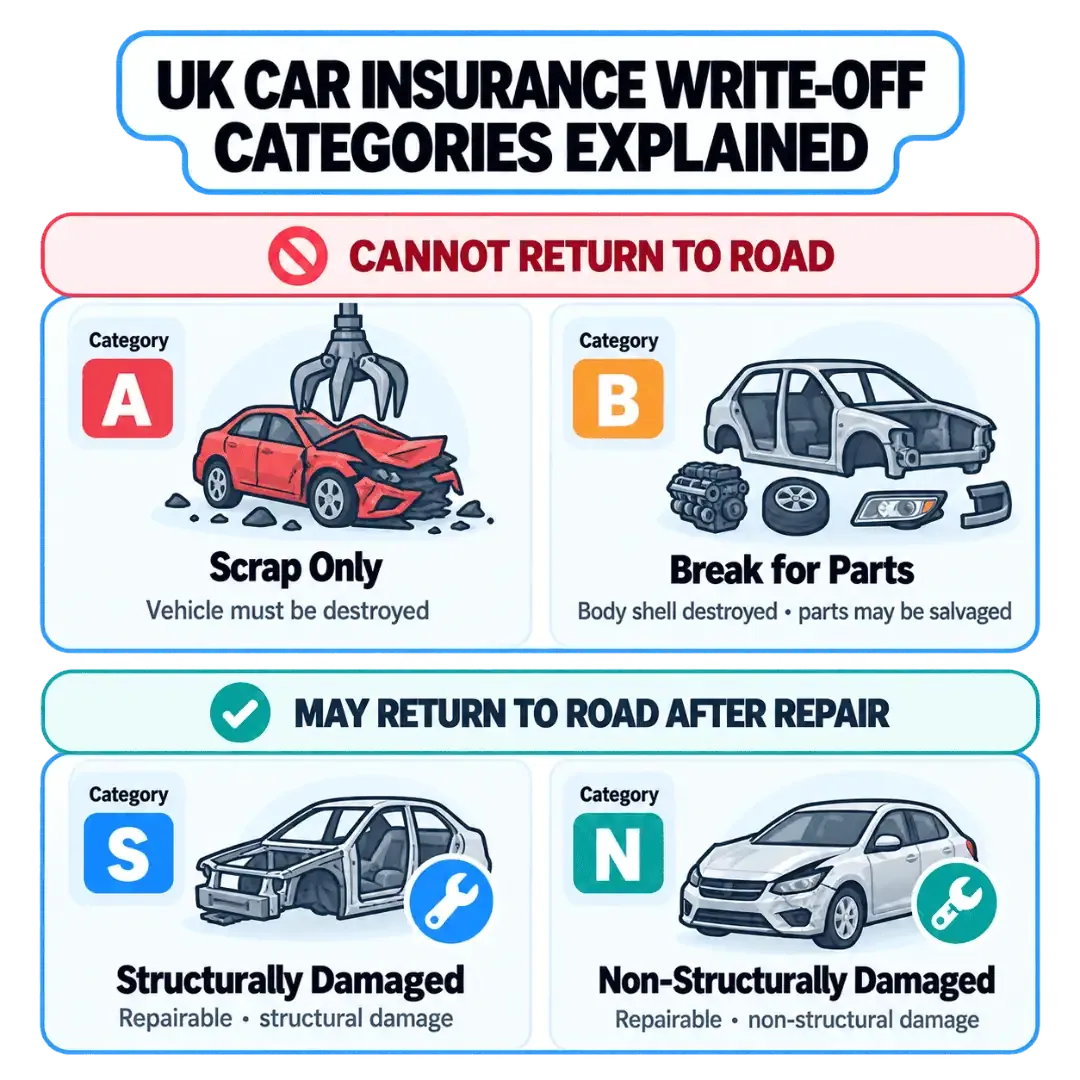
The key steps involved when a car is declared a write-off are outlined below.
- Assessment of the Vehicle: The insurer inspects the damage and decides whether the car should be written off based on its condition, repair costs, and safety.
- Transfer of Vehicle Ownership: The insurer takes ownership of the vehicle unless you choose to retain a Category S or N car.
- Offer of a Settlement: The insurer provides a settlement and arranges the vehicle’s scrappage or salvage sale where applicable.
- Notification to the DVLA: The car owner must notify the DVLA that the vehicle has been written off and return the V5C logbook, while keeping the yellow trade slip for records. Vehicle owners who retain a Category S or N vehicle can request a duplicate logbook using DVLA Form V62.
Note: Category S and N vehicles can be repaired and returned to the road, but they retain a permanent write-off record in vehicle history databases such as CarVeto.
Should I Buy a Cat S or Cat N Write-Off Car?
Yes, you can buy a Cat S or Cat N write-off car, but the decision depends on the vehicle’s repair quality, safety, insurance costs, and potential resale value.
These vehicles offer good value compared to similar cars without a write-off history, but thorough checks are essential before purchase.
A Cat S car has sustained structural damage to areas such as the chassis, crumple zones, or suspension.
You should therefore consider buying one only when the repairs have been professionally completed, the repair documentation is thorough, and an engineer confirms that the vehicle is structurally safe.
These vehicles require DVLA re-registration after repair, and insurance may be limited or expensive.
A Cat N car has non-structural damage, such as damage to the electrics, panels, or interior.
You should consider buying one when safety systems such as ABS and airbags are intact or properly replaced and complete repair records are available.
These vehicles do not require DVLA re-registration and are cheaper to repair and insure than Cat S cars, although their write-off history affects resale value.
An independent inspection, complete repair documentation, and a full vehicle history check help you decide whether the potential savings make the purchase worthwhile.
You can use our Car Write-Off Check to verify MOT status, mileage, and previous damage dates before making a purchase.
Does a Write-Off Affect Resale Value?
Yes, an insurance write-off reduces a vehicle’s resale value because the permanent write-off record lowers buyer confidence and makes the car harder to sell.
Buyers are also concerned about the quality of previous repairs, and insurance restrictions or higher premiums further reduce demand and the price a seller can demand.
The resale impact varies by write-off category.
Category A and B vehicles cannot return to the road as complete cars, so they have no normal resale value as road-going vehicles and are limited to scrappage or usable parts.
Category S vehicles can be repaired and returned to the road, but their structural damage history creates greater buyer concerns and reduces their resale prospects.
Category N vehicles have better resale potential because the damage is non-structural, although the write-off record still affects buyer confidence and selling price.
A vehicle’s repair history, quality of repairs, remaining write-off record, and insurance availability all influence its resale value.
A well-documented repair history provides greater reassurance, but a write-off vehicle will generally be worth less than a comparable car with no write-off history.
How Much Will I Get If My Car Is Written Off?
Your insurer will usually base the payout on your car’s pre-accident market value, minus your policy excess.
This amount forms the final settlement for your written-off car.
Repair costs can also affect whether the insurer decides to write off the car.
A vehicle may be written off when repair costs reach around 50 to 70% of its market value.
Several other factors can affect the amount you receive.
These include outstanding finance, fault, keeping the vehicle, and GAP insurance.
The insurer’s valuation may also differ from the cost of replacing your car.
The final settlement may therefore not cover the full amount needed to buy a similar vehicle.
How Long Does It Take to Get Paid Out After a Car Is Written Off in the UK?
It takes 7 to 28 days to get paid out after a car is written off in the UK.
The exact timeframe varies depending on the speed of the assessment, how quickly the write-off category is assigned, and how promptly you accept the insurer’s settlement offer.
Some claims may take 14 to 30 working days, depending on the claim and insurer.
The car write-off payout timeline is given below.
- Day 1 – Claim submission: You report the accident and provide the required documents, including the V5C, damage photos, and any requested quotes.
- Days 2-5 – Vehicle inspection: A certified engineer inspects the car to assess the damage and determine whether it qualifies as a total loss.
- Days 5-10 – Valuation and categorisation: The insurer determines the car’s pre-accident market value and assigns a write-off category, such as A, B, S, or N.
- Days 10-15 – Settlement offer: The insurer provides a payout proposal based on the car’s market value, minus the policy excess.
- Days 15-28 – Payment issued: Funds are transferred to your bank account or finance provider, depending on the ownership status. The final payment may reach your bank account within 3-5 working days after you accept the settlement offer and payment is confirmed.
What Happens to My Insurance Policy After My Car Is Written Off?
Your car insurance policy is cancelled after your car is written off.
A temporary replacement vehicle cover continues for 7 to 14 days, depending on your policy terms.
The next steps after cancellation depend on whether you keep the vehicle, replace it, or stop driving.
A retained Category S or N car must be reported to your insurer because some providers offer cover after an inspection, while others may refuse to insure written-off vehicles.
Your payment arrangements also change when the insurance policy ends.
Annual policies qualify for a refund for unused cover, although cancellation or administration fees apply, and refunds depend on there being no further active claims.
Monthly policies still have outstanding instalments, which most insurers deduct from the final payout before the policy is closed.
The policy excess is deducted from the insurance payout and is not refundable after the policy is cancelled.
Add-ons such as legal expenses or breakdown cover are rarely refunded, although available credit is applied to a replacement policy with the same insurer.
A write-off claim also affects your no-claims bonus, depending on your insurer’s terms and whether the bonus is protected.
This could increase the cost of future insurance if your no-claims discount is reduced following the claim.
You should notify the DVLA of the vehicle’s write-off classification and arrange new cover before driving again once the insurance has been cancelled.
Written confirmation of cancellation also helps you check for remaining charges, refunds, and automatic renewals.
Can I Insure a Car That Has Been Written Off?
Yes, you can insure a car that has previously been written off, but not every insurer will provide cover for Cat S and Cat N vehicles.
This car must be properly repaired, meet the required safety standards, and be legally roadworthy before it is insured.
You must disclose the vehicle’s previous write-off status when arranging insurance.
Failing to provide accurate information could invalidate your policy or affect a future insurance claim.
Specialist brokers are more likely to offer suitable and competitive insurance cover for repaired write-off cars.
Premiums are higher for vehicles with a previous write-off history, particularly Cat S cars, and some insurers offer fewer cover options.
You should confirm that the insurer will cover the written-off vehicle before buying it to avoid problems arranging insurance later.
A written-off history also reduces the vehicle’s market value, which results in a lower insurance payout if the car is written off again.
You can run a Motor Insurance Bureau check through our database to check the vehicle’s insurance history before making a purchase.
What Can I Do if I Do Not Agree With the Write-off Decision?
You can challenge the write-off valuation when you believe your insurer has undervalued your car.
Insurers rely on automated tools that may overlook key features, upgrades, or exceptional conditions.
A valuation may also miss factors such as factory-fitted extras or high-spec trim, recent servicing, premium tyres, mechanical work, outstanding cosmetic condition, regional price differences, and limited vehicle availability.
This also affects the vehicle’s market value.
You can follow the steps mentioned below to challenge the valuation.
- Do not accept the settlement yet: Hold off on accepting the insurer’s first offer until you have checked whether the proposed payout fairly reflects your car’s market value.
- Verify the vehicle details: Check that the insurer has recorded the correct make, model, year, mileage, specification, trim level and factory-fitted extras, as incorrect details result in an inaccurate valuation.
- Gather supporting evidence: Collect at least three comparable UK vehicle listings from reputable platforms such as AutoTrader, Parkers or Motors.co.uk. Supporting evidence should include service records, invoices for upgrades or mechanical work, recent photos, and evidence of the car’s condition.
- Submit a written appeal: Write to your insurer’s valuation team, explain why you believe the car has been undervalued, attach your supporting evidence, and clearly request a reassessment of the settlement.
- Use a professional assessor: Consider hiring a qualified vehicle engineer to provide an independent written valuation. This can be particularly useful for higher-value or borderline cases where the insurer’s assessment remains disputed.
- Escalate if needed: Allow the insurer to resolve the complaint first. You can contact the Financial Ombudsman Service to review the issue if it remains unresolved after 8 weeks or if you have received a final written response. This service is free and impartial.
Most valuation disputes are resolved without formal escalation when you provide clear evidence to support your appeal.
Revised offers follow within 7-14 days after the insurer receives your evidence, and an independent report can strengthen your case in borderline disputes.
Can I Buy Back My Written-Off Car?
Yes, you can buy back a written-off car from your insurer when the vehicle is classified as Category S or Category N.
Buying a write-off car allows you to keep the vehicle after it has been declared a total loss.
Your insurer will deduct the vehicle’s salvage value from your insurance payout when you choose to keep it.
You will then be responsible for the repair costs and for ensuring the car meets all required safety and roadworthiness standards.
Category S vehicles must be re-registered with the DVLA before they legally return to the road.
Category A and Category B vehicles cannot be bought back because they cannot be returned to the road.
The buy-back option should be discussed with your insurer early in the claim, as a car sold to a salvage yard or sent for crushing cannot be retrieved later.
How Can I Check the Write-Off Status of My Car?
You can check the write-off status of your car with CarVeto’s Car Write-Off Check by using its registration number to access a comprehensive vehicle history report.
This report confirms whether the vehicle has previously been written off and shows its recorded category.
Our Car Write-Off Check helps you verify a vehicle’s history before buying or selling it, giving you greater confidence in its condition and background.